Pierre Part’s biggest natural hazard is hurricanes
Most of the natural-hazard damage FEMA expects in Pierre Part comes from hurricanes, and overall the risk is very high for a U.S. community. 7 federal disasters brought FEMA money into town.
What stands out about Pierre Part’s weather risks
Read from FEMA’s records below. The page puts what stands out first.
Does Pierre Part flood? No paid flood claims on record
FEMA’s records show no paid flood insurance claims in Pierre Part. That’s not a promise: most homes don’t carry flood insurance, so small floods go unrecorded.
Pierre Part isn’t in FEMA’s Community Rating System, which cuts flood insurance up to 45% in towns that do extra flood-proofing.
Insurance rates: Assumption Parish.How exposed is Pierre Part?
FEMA expects yearly storm and flood damage to homes and buildings here to be higher than in 94% of U.S. communities, mostly from hurricanes and inland flooding.
Rated higher than 399 of the 483 Louisiana towns we cover.
Pierre Part is smaller than a census tract, so it shares the figures of the tract around its center.
What Pierre Part faces
Each hazard’s share of the damage FEMA expects here, and how it compares with the rest of the country.
Hurricanes
Inland flooding
Tornadoes
7 federal disasters brought FEMA money to Pierre Part
Disasters that paid out in Pierre Part itself (aid to households or repair grants to Pierre Part) and its biggest flood years.
- 2024Hurricane Francine293 households applied for aid$962K aid approved
- 2021Hurricane Ida951 households applied for aid$548K aid approved
- 2016Severe Storms and Flooding2 households applied for aid$2K aid approved
- 2012Hurricane Isaac71 households applied for aid$40K aid approved
- 2008Hurricane Gustav934 households applied for aid$1.1M aid approved
- 2005Hurricane Rita6 households applied for aid$4K aid approved
Show all 7
- 2005Hurricane Katrina562 households applied for aid$572K aid approved
Assumption Parish has had 36 natural disasters declared since 1953, most often hurricanes and floods.
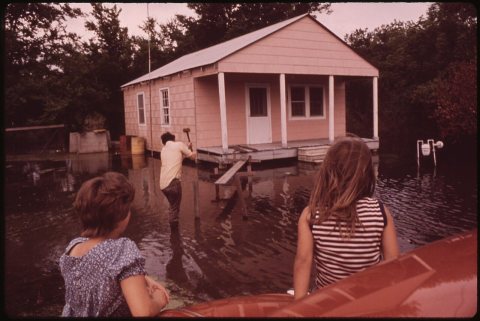 1973 · IN THE SPRING OF 1973 THE MISSISSIPPI RIVER REACHED ITS HIGHEST LEVEL IN MORE THAN 150 YEARS. UNPRECEDENTED FLOODING...…
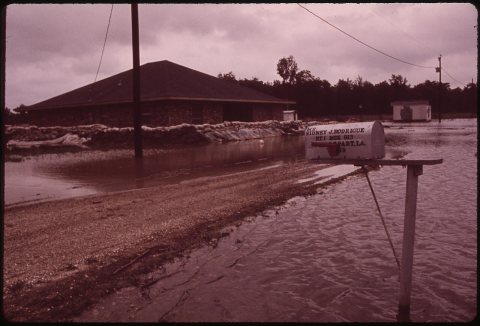 1973 · IN THE SPRING OF 1973 THE MISSISSIPPI RIVER REACHED ITS HIGHEST LEVEL IN MORE THAN 150 YEARS. UNPRECEDENTED FLOODING...…
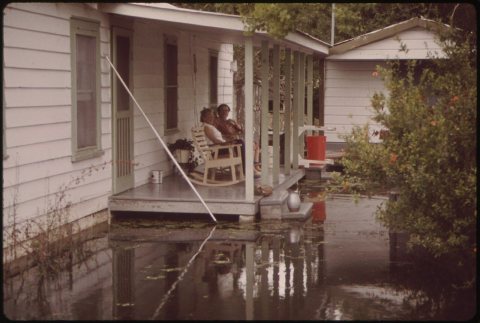 1973 · IN THE SPRING OF 1973 THE MISSISSIPPI RIVER REACHED ITS HIGHEST LEVEL IN MORE THAN 150 YEARS. UNPRECEDENTED FLOODING...…
Get ready for what Pierre Part actually faces
A short kit for its top hazards, what to check before you buy, and where neighbors get alerts.
- The season runs June through November and peaks from mid-August to mid-October.
- Bring in porch furniture and anything the wind can throw.
- Fill the gas tank and charge phones before the storm arrives.
- Turn around at flooded roads: a foot of moving water can carry off a car.
- Flood insurance usually takes 30 days to start, so buy it before the forecast.
- Keep papers and medicines up high, in a grab-and-go bag.
- Pick your spot now: the lowest floor, an inside room, no windows.
- A watch means be ready; a warning means take cover now.
- Keep shoes and a flashlight by the bed.
- Look up the address on FEMA’s flood map.
- Ask the seller or landlord whether it has ever flooded, and what flood insurance costs there.
- Get a flood insurance quote early: policies usually start 30 days after you buy.
Know where neighbors sign up for alerts? Add it to the Handbook so everyone has it.
Most disasters here begin in August–October
The month each of Assumption Parish’s 36 declared disasters began, since 1953.
What these numbers can and can’t tell you
- An average, not a forecast. FEMA’s National Risk Index estimates the damage 18 kinds of natural hazards cause in a typical year, from decades of records and models. A quiet decade can follow a bad year.
- Compared by rate. “Higher than N%” compares yearly damage as a share of what’s there, so a big city isn’t rated riskier just for having more buildings.
- Money that reached town. Flood claims are matched to Pierre Part’s own flood-insurance community; household aid to the registrant’s city; repair grants to Pierre Part.
- It follows property value. FEMA’s model weighs damage to buildings, so a place that recently lost many homes can rate lower than it feels.
Storm stories
Memories, warnings and help from neighbors in Pierre Part.
Your answer becomes a post in Town Square.
Sources: FEMA National Risk Index (December 2025); OpenFEMA: NFIP redacted claims, multiple-loss properties, community status book and residential penetration rates, housing assistance (owners and renters), public assistance funded projects, hazard mitigation properties and disaster declarations. Census tracts: U.S. Census Bureau. Preparedness tips: Ready.gov. An average of past damage, not a forecast.